Introduction
Both Sukuk and conventional bonds are tools used by governments, banks, and companies to raise capital from investors. On the surface, they can look very similar:
- Investors provide money upfront
- Periodic payments are made
- Capital is repaid at maturity
But underneath, the structures are fundamentally different.
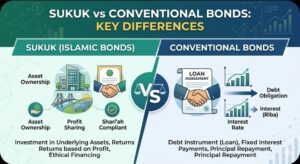
A conventional bond is primarily a debt instrument based on interest payments. Sukuk, by contrast, are structured around ownership, leasing, trade, or partnership arrangements in compliance with Islamic finance principles.
This distinction affects:
- Legal structure
- Risk allocation
- Investor rights
- Asset backing
- Return generation
- Market behavior
- Regulatory treatment
1. Core Philosophical Difference
Conventional Bonds: Debt-Based Finance
A conventional bond represents:
A loan from investors to the issuer.
When investors buy bonds:
- They lend money
- Issuer promises repayment
- Interest (coupon) is paid periodically
The relationship is creditor-debtor.
Example:
- Government issues 10-year bond
- Pays 8% annual interest
- Returns principal at maturity
The investor’s return comes from:
- Interest income
- Not ownership of productive assets
Sukuk: Asset-Linked or Asset-Based Finance
Sukuk avoid interest (riba), which is prohibited in Islamic finance.
Instead:
- Investors obtain ownership interest in assets, usufructs, projects, or ventures
- Returns come from asset performance, lease income, or profit-sharing
The relationship is more investment-oriented than debt-oriented.
Example:
- Investors collectively own a power plant
- Plant generates lease income
- Income distributed to Sukuk holders
Returns arise from:
- Economic activity
- Asset usage
- Business profit
- Trade margin
rather than pure lending interest.
2. Legal Structure
Conventional Bond Structure
A bond is straightforward legally.
Structure:
- Issuer borrows money
- Investors become creditors
- Contract specifies:
- Coupon rate
- Maturity
- Repayment obligations
No transfer of ownership in assets is necessary.
Legal Nature:
- Debt obligation
- Enforceable repayment promise
Sukuk Structure
Sukuk are structurally more complex because Sharia compliance requires real economic linkage.
Typically involves:
- Special Purpose Vehicle (SPV)
- Asset transfer
- Lease agreements
- Purchase undertakings
- Profit distribution mechanisms
Basic Sukuk Process:
- SPV created
- Assets transferred to SPV
- Investors buy Sukuk certificates
- SPV uses funds to acquire/project finance
- Income generated from asset/project
- Income distributed to investors
Legal Nature:
Depends on Sukuk type:
- Ownership
- Partnership
- Lease rights
- Profit-sharing participation
3. Interest vs Profit
Bonds: Interest-Based Returns
Bondholders receive:
- Fixed or floating interest
Example:
- 7% coupon annually
Payment obligation exists regardless of project performance.
Even if issuer struggles:
- Interest still legally due
- Unless default occurs
This fixed-interest model is central to conventional finance.
Sukuk: Profit or Asset Income
Sukuk returns must come from:
- Lease payments
- Business profits
- Asset revenue
- Trade gains
Example: Ijarah Sukuk
- Investors own leased asset
- Issuer pays rent
- Rent distributed to investors
Example: Musharaka Sukuk
- Investors share actual project profit
Returns are linked to economic activity.
4. Asset Backing
Bonds
Most bonds:
- Are unsecured promises
- Not tied directly to assets
Government bonds especially rely on:
- Sovereign creditworthiness
Corporate bonds rely on:
- Company balance sheet
- Cash flow capacity
Some bonds are secured, but many are not.
Sukuk
Asset linkage is essential.
Sharia principles require:
- Tangible underlying assets
- Identifiable economic activity
Assets may include:
- Real estate
- Infrastructure
- Equipment
- Transportation assets
- Energy facilities
This creates stronger linkage between finance and real economy.
5. Risk Allocation
Conventional Bonds
Bondholders primarily face:
- Credit risk
- Interest rate risk
- Inflation risk
But generally:
- They do not share operational business risk directly
Bondholders expect payment regardless of business performance.
Risk transfer is asymmetric:
- Borrower bears operational risk
- Investors expect contractual interest
Sukuk
Islamic finance emphasizes:
Risk-sharing rather than risk-transfer.
Depending on structure:
- Investors may share asset performance risk
- Returns may fluctuate
- Asset impairment can affect payouts
This aligns finance more closely with underlying economic activity.
However, many modern Sukuk are structured to provide stable returns similar to bonds, reducing practical differences in some markets.
6. Sharia Compliance
Bonds
Conventional bonds typically violate Islamic finance principles because:
- They involve interest (riba)
- Can involve excessive uncertainty (gharar)
- May finance prohibited sectors
Examples of prohibited sectors:
- Gambling
- Alcohol
- Weapons
- Certain speculative activities
Sukuk
Sukuk must comply with:
- Prohibition of riba
- Asset-backed requirements
- Ethical investment standards
- Risk-sharing principles
Sharia supervisory boards review structures to ensure compliance.
7. Pricing and Valuation
Bonds
Bond pricing depends on:
- Interest rates
- Credit rating
- Inflation expectations
- Central bank policy
- Market liquidity
When rates rise:
- Bond prices fall
Sukuk
Sukuk pricing is influenced by:
- Similar market forces
- Asset quality
- Lease income stability
- Sharia structure credibility
In practice, many Sukuk are benchmarked against conventional rates like:
- SOFR
- LIBOR (historically)
This is one criticism from some Islamic scholars who argue modern Sukuk sometimes mimic conventional debt too closely.
8. Types of Sukuk
Ijarah Sukuk
Lease-based.
Most widely used globally.
Characteristics:
- Predictable cash flow
- Asset leased to obligor
- Similar to fixed-income instruments
Musharaka Sukuk
Equity partnership.
Characteristics:
- Shared ownership
- Profit-and-loss sharing
- Higher risk/reward
Mudaraba Sukuk
Manager-investor partnership.
Characteristics:
- One party manages
- One provides capital
- Profit shared
Murabaha Sukuk
Trade-finance based.
Characteristics:
- Cost-plus financing
- Less tradable in some jurisdictions
9. Global Market Development
Major Sukuk markets include:
- Malesia
- Saud Arabia
- United Arab Republic
- Indonesia
Malaysia is considered a global leader in:
- Sukuk innovation
- Regulatory frameworks
- Islamic capital market infrastructure
Sukuk markets now finance:
- Airports
- Renewable energy
- Government budgets
- Railways
- Smart cities
10. Economic Implications
Conventional Bond Markets
Advantages:
- Deep liquidity
- Simpler structures
- Large investor base
- Efficient capital raising
Challenges:
- High debt dependency
- Interest burden
- Financialization concerns
Sukuk Markets
Advantages:
- Ethical finance orientation
- Asset-backed discipline
- Broader investor inclusion
- Access to Islamic liquidity pools
Challenges:
- Legal complexity
- Higher structuring costs
- Sharia interpretation differences
- Smaller secondary markets
11. Sukuk Criticism
Some critics argue modern Sukuk:
- Replicate conventional bonds economically
- Use complex legal engineering
- Offer “synthetic” compliance
For example:
- Fixed returns
- Purchase guarantees
- Benchmarking to interest rates
This creates debate between:
- Conservative scholars
- Market practitioners
The debate centers on:
Whether modern Sukuk fully embody Islamic economic philosophy or merely adapt conventional finance into Sharia-compliant form.
12. Ethiopia and Future Potential
For , Sukuk could become important because:
- Large underserved Islamic finance market
- Infrastructure financing needs
- Growing capital market reforms
- Expanding investor base
Potential sectors:
- Energy
- Housing
- Agriculture
- Transport infrastructure
The emergence of the may eventually support Sukuk listings and secondary trading.
However, Ethiopia still needs:
- Stronger Islamic capital market regulation
- Sharia governance frameworks
- Investor education
- Tax neutrality rules
- Asset securitization infrastructure
Final Comparison
| Area | Sukuk | Conventional Bonds |
|---|---|---|
| Foundation | Asset/partnership based | Debt based |
| Investor role | Partial owner/investor | Creditor |
| Return source | Profit/rent | Interest |
| Sharia compliance | Yes | Usually No |
| Asset backing | Required | Optional |
| Risk structure | Shared risk | Borrower-centered |
| Complexity | Higher | Lower |
| Ethical screening | Required | Not required |
| Market size | Smaller | Much larger globally |
Conclusion
Sukuk are not simply “Islamic bonds.” They represent a different philosophy of finance centered on:
- asset linkage,
- ethical investment,
- and risk-sharing.
Conventional bonds prioritize efficient debt financing through contractual interest obligations. Sukuk seek to connect finance more closely with real economic activity and Sharia principles.
In practice, modern markets have narrowed some differences, especially as Sukuk evolved to compete globally with conventional fixed-income instruments. Still, the structural, legal, and philosophical distinctions remain significant — especially for countries like that are developing both Islamic finance and modern capital markets simultaneously.
Feeling lucky today! The bonuses here are actually generous and easy to claim. I am definitely staying with luckybet7game for a long time.
Really impressed with the game variety here. There is something for everyone and the bonuses are actually fair. Definitely checking out krtwincasino again tomorrow.
I’ve tried a few sites lately but this one feels the smoothest. The payouts are quick and the interface is very user friendly. Highly recommend checking out phjiliuno if you love slots.
Fast deposits and even faster withdrawals. It is hard to find a site that doesn’t make you jump through hoops. Glad I found pheevip.
Really liking the current promotions they have going on. It feels like they actually reward loyal players. Give in11ic a shot!
The atmosphere is electric and the games are truly engaging. I’ve had a few big wins here and the withdrawal process was a breeze. phfierycasino is the real deal!
I always check here for the latest promos and game updates. It keeps me in the loop so I never miss a big jackpot opportunity. Thanks to phokbetupdate for the info.